What Is the Right of Rescission? Your 3-Day Window to Cancel a Home Loan
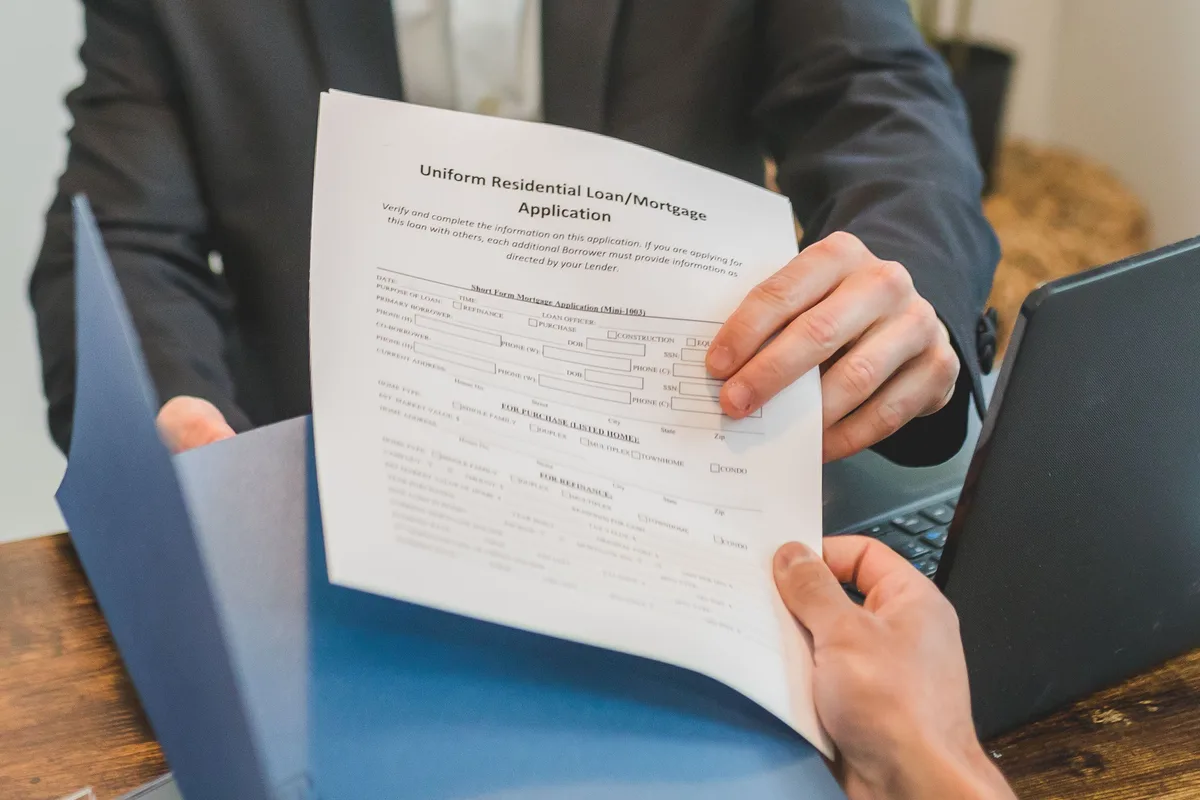
Key takeaways
- The right of rescission lets you cancel certain home loans within three business days of signing, for any reason, under Regulation Z (12 CFR 1026.23).
- It covers refinances, home equity loans, and HELOCs secured by your primary home. A purchase loan secured by the home you are buying is exempt, but a loan secured by your existing home to buy or build another one, such as a bridge loan, can still be rescindable.
- The three-day clock starts on the latest of three events: signing, receiving the Notice of Right to Cancel (two paper copies, or one electronic copy under the E-Sign Act), and getting all material disclosures.
- For rescission, Saturdays count as business days, but Sundays and federal holidays do not, so count the days yourself, and if your count does not match the date printed on the notice, act promptly and get advice.
- After you cancel, the lender has 20 calendar days to return your money and to begin terminating its lien; commentary says it must start that process in time, though finishing the release can take longer.
- The limited same-creditor refinance exemption applies only to your original creditor or its corporate successor, not to an assignee who merely bought your loan, so refinancing with a new holder can carry the full rescission right.
Imagine you just signed a stack of papers to refinance your house or take out a home equity loan. You get home, read the fine print again over coffee, and something feels off. Maybe the rate is higher than you remembered, maybe a fee surprised you, or maybe you simply changed your mind. Here is the part most people never learn until they need it: for certain home loans, federal law gives you a few days to cancel the whole thing, with no penalty and no need to explain yourself.
That protection is called the right of rescission. "Rescind" is just a lawyer's word for cancel. It is written into the Truth in Lending Act and spelled out in detail in a federal rule known as Regulation Z. It does not apply to every loan, and the way the clock starts trips up a lot of people, so it is worth understanding before you ever sit down at a closing table.
What the right of rescission actually is
The right of rescission is a federal consumer protection that lets you unwind certain credit transactions secured by your home within three business days after you become obligated, for any reason or no reason at all. The rule lives at 12 CFR section 1026.23 of Regulation Z, which carries out the Truth in Lending Act, and it is enforced by the Consumer Financial Protection Bureau. The regulation is blunt about the effect of canceling: once you properly rescind, "the security interest giving rise to the right of rescission becomes void and the consumer shall not be liable for any amount, including any finance charge."
In plain terms, that means the lender's lien on your home disappears, and you do not owe the finance charge or fees tied to that loan. It is one of the strongest consumer rights in all of lending, which is exactly why Congress attached it to the single asset most families cannot afford to lose: the roof over their heads.
Two things make this right unusual. First, you do not need a reason. Buyer's remorse is enough. Second, the lender cannot disburse the money or start work until the window closes, so in most refinances the funds do not actually move until your three days are up. That waiting period is not red tape for its own sake. It is a built-in cooling off period designed to protect you.
Why this right exists at all
The right of rescission was created to deal with high-pressure lending aimed at homeowners. Decades ago, some lenders would talk people into loans secured by their homes using aggressive sales tactics, then disburse the money fast so the borrower felt locked in. Congress decided that when your primary home is on the line, you deserve a short, guaranteed window to step back, reread the terms, and walk away cleanly if the deal is not what you thought.
That history still shapes how the rule behaves today. The protection is generous on purpose, and the penalties for lenders who get the paperwork wrong are severe, as you will see when we get to the three-year window. The goal has always been the same: give ordinary homeowners a real chance to reconsider a deal that puts their house at risk.
When the three-day clock actually starts
This is the single most misunderstood part of the whole rule. The three business days do not simply start when you sign. According to section 1026.23, you may cancel "until midnight of the third business day following consummation, delivery of the notice required by paragraph (b) of this section, or delivery of all material disclosures, whichever occurs last."
Read that last phrase slowly, because it does a lot of work. The clock starts on the latest of three separate events, not the earliest. Those three events are:
- You become obligated on the loan, usually by signing the note at closing.
- You receive the written Notice of Right to Cancel. The lender must give this notice to each person entitled to cancel. On paper that is two copies per person, but if the lender delivers it electronically and follows the consumer-consent rules of the federal E-Sign Act, a single electronic copy to each person is enough. An electronic copy delivered that way is fully compliant, so it does not stretch your cancellation window the way a missing notice would.
- You receive all of the "material disclosures," which include the annual percentage rate, the finance charge, the amount financed, the total of payments, and the payment schedule.
Normally all three happen on the same day at closing, so the window runs cleanly for three business days after that. But if the lender hands you the disclosures late or fails to deliver the notice at all, the start date moves to whichever event came last. The CFPB gives a clean example of counting: if everything is delivered on a Friday with no holiday in between, your deadline is midnight the following Tuesday.
One more wrinkle catches people off guard. For rescission, "business day" is defined generously. The CFPB confirms that business days "include Saturdays, but not Sundays or legal public holidays." So a Saturday counts against your window even though the bank branch is closed, while a Sunday or a federal holiday does not. If you want to cancel, do not wait until the last afternoon and assume a weekend buys you extra time. Count carefully, and when in doubt, act early.
Which loans it covers, and which it does not
This is where a lot of hope gets dashed, so let us be precise. The right of rescission applies to credit transactions where the lender takes a security interest in your principal dwelling, meaning the home you actually live in. The classic examples are a refinance, a home equity loan, and a home equity line of credit, or HELOC.
The rule carves out several exceptions, but they are narrower than they first appear. The most important one is right there in the regulation: "a residential mortgage transaction" is exempt. That is the legal label for a loan secured by the very home you are using the money to buy or build. In other words, a standard purchase mortgage, where the house you are buying is the collateral, carries no right of rescission. As the CFPB puts it, if you are buying a home with that kind of loan, "you do not have a right to cancel the loan once the closing documents are signed." The logic is that a purchase involves a seller who is relying on the deal closing, so you cannot simply unwind it after the fact.
But notice the careful wording. The exemption turns on which home secures the loan, not just on what you plan to do with the money. CFPB commentary makes this explicit: if you borrow against a home you already live in to help acquire or build a different principal dwelling, that loan is still subject to the right of rescission, because it is secured by your current principal dwelling. A bridge loan is the classic example. So "I am using this money to buy or build a home" does not by itself mean the rescission right is gone. The real question is whether the collateral is the new home being acquired or the existing home you are living in.
Several other situations are also excluded. If you understand which bucket your loan falls into, you will know whether the window exists at all.
The same-creditor refinance rule deserves a closer look, because it is widely misunderstood. The limited exemption applies only when you refinance with the original creditor, defined in the rule as the creditor your loan agreement was first made payable to, or a company that stepped into its shoes through a merger, consolidation, or acquisition. For that narrow group, only the "new money," the amount advanced beyond your existing balance, unpaid finance charges, and refinancing costs, is subject to cancellation. Here is the catch many borrowers miss: mortgages are sold and assigned constantly. If your loan was transferred to a different holder and you later refinance with that assignee, the assignee is generally not the original creditor, so the full right of rescission applies to the entire refinance, not just the new money. Whoever happens to hold your loan today is not the test. The test is whether your new lender is the original creditor or its corporate successor, so it is worth asking directly.
Because home equity borrowing is where this right shows up most often, it helps to understand the products themselves before you sign. Our guide on a home equity loan versus a HELOC walks through how each one works and what the trade-offs are, which can save you from needing the rescission right in the first place.
If the loan you are reviewing is a home equity loan, it also helps to picture what living with that balance looks like. The estimator below is a plain hypothetical, not a quote, and it uses the loan's fixed note rate rather than its APR, leaving out fees, closing costs, taxes, and insurance. Moving the balance, the interest rate, and the monthly payment shows roughly how long the debt would stick around and what it would cost you in interest. It is a useful gut check to run during your cancellation window, before any money actually moves.
The three-year window almost nobody expects
Here is the twist that gives this rule its teeth. The three business day window is the normal case, but it assumes the lender did its job. If the lender never delivers the required Notice of Right to Cancel, or never gives you all the material disclosures, or delivers them with real errors, the window does not close in three days. It can stretch all the way to three years.
The regulation says that if the required notice or material disclosures are not delivered, the right to rescind "shall expire 3 years after consummation, upon transfer of all of the consumer's interest in the property, or upon sale of the property, whichever occurs first." So the long window is capped at three years and also ends if you sell or transfer the home before then. Courts have treated meaningful disclosure mistakes, such as a materially understated APR, as the kind of error that can keep this extended right alive.
The table above is not meant to scare anyone. It simply shows why lenders take the paperwork so seriously, and why the two deadlines are measured in completely different ways. A clean closing gives you a short, predictable window counted in a handful of business days. A sloppy one can expose the lender for years of calendar time. The U.S. Supreme Court added an important clarification in a 2015 case, Jesinoski v. Countrywide Home Loans, holding that a borrower exercises the extended right simply by mailing written notice to the lender within the three years. You do not have to file a lawsuit first to preserve it. That said, the extended window often ends up in court anyway because lenders dispute whether a violation really happened, so it is not a casual do-over. Think of it as a backstop for genuine disclosure failures, not a general escape hatch.
How to cancel the right way
If you decide to use your three-day window, how you cancel matters just as much as when. The single most important rule is that cancellation must be in writing. A phone call to your loan officer does not count, no matter how friendly or how clearly you say you are backing out. The regulation requires written notice, and courts have enforced that strictly.
The lender is required to give you a form you can use to cancel, usually the model Notice of Right to Cancel, but you are not locked into that form. Any clear written statement that you are canceling will do, as long as it identifies the transaction and you send it in time. What you cannot do is let the midnight deadline on the third business day pass without sending anything.
A few practical habits protect you here. Keep the Notice of Right to Cancel the lender gave you, along with any electronic copy, because it is supposed to list the exact date your window closes. Then count the days yourself from the latest of the three triggering events and compare the two. If they match, you have your answer. If they do not, because the notice arrived late, a disclosure was missing, or the printed date simply looks wrong, resist the urge to decide on your own which date is correct. A wrong expiration date is not a harmless typo. An inaccurate or incomplete notice can itself be a defective disclosure that affects your rescission rights, sometimes in your favor by extending the window. The safe move when the dates disagree is to treat the earlier of the two as your working deadline, act promptly rather than waiting, and get advice from a qualified attorney or a HUD-approved housing counselor about the discrepancy before any deadline passes.
How you send the cancellation also matters, and the rule draws a sharp line here. Under section 1026.23(a)(2), a notice sent by mail counts as given the moment you drop it in the mailbox, even if the lender does not receive it for several days. A notice sent another way, such as fax or hand delivery, counts only when it actually reaches the creditor's designated place of business. So mailing before midnight on the final day protects you even if the post is slow, while hand delivery has to physically arrive by the deadline. Whatever method you choose, send it in a way you can prove, such as certified mail with a return receipt, a fax with a confirmation page, or hand delivery with a dated acknowledgment, and keep a copy of whatever you send. If there is ever a dispute about timing, that paper trail is what decides it.
If you are juggling several accounts and want a single place to keep an eye on your loans and credit profile while a refinance is in motion, a monitoring tool such as WalletHub Premium can help you track the accounts tied to your home. It is no substitute for reading your closing documents, but it can make it easier to notice when a new loan actually posts.
What happens after you cancel
Canceling does not leave things in limbo. The regulation sets clear duties for the lender once you rescind. Within 20 calendar days after receiving your notice, the creditor must "return any money or property that has been given to anyone in connection with the transaction" and "take any action necessary to reflect the termination of the security interest." The 20 days is a firm deadline for returning your money, but the official commentary is careful about the lien itself: it says the 20-day period is the time within which the creditor must begin the security-interest termination process, not finish every step, and the creditor stays responsible for seeing that process through to completion. So the paperwork that formally clears the lien from your title can take a little longer, as long as the lender starts it on time. Notice too that the lender's 20-day clock runs from when your notice is received, even though your own deadline to send it is measured when you mail it.
There is a default sequence to the unwind. In the ordinary, uncontested case the lender acts first by returning money and starting to void the security interest, and then you return any loan funds you received. If the lender fails to meet its obligations, the law can shift the balance further in your favor. But this order is not carved in stone. Regulation Z lets a court modify these tender procedures, and the official commentary explains that when a lender contests your right to rescind, a court will normally decide first whether you actually have the right and how much each side owes before setting the steps for returning money or property. So the lender-first sequence is the rule of thumb for a clean, uncontested cancellation, not an iron guarantee in a disputed one. The clean takeaway is that rescission is designed to put both sides back roughly where they started, as if the loan never happened, rather than to punish anyone who simply changed their mind in time.
It is also worth knowing what rescission does not do. It cancels the specific covered loan transaction, not any unrelated obligation, and it is not a way to make an existing debt vanish. What happens to an old loan depends on timing. In the standard three-day case the money has not moved yet, so if you rescind a refinance before the lender disburses the funds and pays off your prior loan, that old loan simply stays in place because the new one never took effect. The picture can be different once money has actually changed hands, which is possible in the extended three-year scenario after a refinance has already funded. By then the new loan may have paid off and satisfied your old mortgage, so rescinding does not automatically revive the prior loan. Instead it unwinds the new transaction and triggers the return-and-tender process described above, which, as noted, is often sorted out in court when the lender disputes the rescission. Either way, canceling affects only the covered transaction you were taking on, not debts that exist independently of it.
Common misunderstandings worth clearing up
Because this right sounds almost too good to be true, myths cling to it. Here are the ones that cause the most trouble.
It is not a general three-day return policy on loans. It applies only to credit secured by your principal dwelling, and only to the covered transactions described above. A car loan, a personal loan, a credit card, and the purchase mortgage secured by the home you are buying do not carry this right under federal law. Some other consumer protections exist for other products, but they are separate rules with their own timelines.
Every co-owner holds the right independently. If you and a spouse both own the home, the lender must give each of you the Notice of Right to Cancel, two paper copies each or one electronic copy each under the E-Sign rules, and either one of you can cancel the whole transaction alone. One owner's signature is enough to unwind it, which is a meaningful protection in households where only one person was driving the deal.
HELOCs get the same treatment, with their own rule. Open-end home equity lines are covered by a parallel section of Regulation Z, section 1026.15, rather than the closed-end rule at 1026.23, but the core idea is the same three business day cooling off period after the account is opened and the required notices and disclosures are delivered. If your HELOC later gets refinanced or restructured, pay attention, because new money can trigger a fresh right to cancel.
The lender cannot talk you out of the window. There is a narrow, rarely used procedure for waiving the waiting period in a genuine, documented personal financial emergency, such as needing funds immediately to stop a foreclosure. It requires a dated, signed, written statement describing the emergency, and it is tightly limited. For almost everyone, the honest answer is that the waiting period simply applies and the money will not move until it ends.
How this fits with the rest of your closing
If you have refinanced recently, you may notice that the rescission window overlaps with another waiting period you now get under the modern disclosure rules, which generally require you to receive your Closing Disclosure at least three business days before closing. Those are two different protections stacked near each other. One gives you time to review terms before you sign, and the right of rescission gives you time to back out after you sign. Regulators have been studying whether these overlapping waiting periods slow down funding, but as of now the rescission right on covered home loans remains in force exactly as described here.
The practical lesson is to use both windows. Read your Closing Disclosure carefully during the days before closing, compare it to the Loan Estimate you received earlier, and then use the rescission window afterward as a final safety check rather than as your first real look at the numbers. The more you understand before you sign, the less likely you are to need the cancellation right at all.
The bottom line
The right of rescission is a quiet but powerful protection built into federal law for one reason: your home is too important to risk on a deal you had no chance to reconsider. If you refinance a loan secured by the home you live in, take out a home equity loan, or open a HELOC on that home, you generally get three business days to cancel for any reason, counted from the latest of three events, and you must cancel in writing before midnight on the third business day.
If the lender botches the required notice or disclosures, that window can stretch to three years, which is why lenders rarely get it wrong on purpose. Know which loans carry the right, count your days carefully, and if the date you calculate does not match the one printed on your notice, treat the discrepancy as a red flag, act promptly, and get advice rather than guessing which date controls. Send any cancellation in a way you can prove. Remember that mailing counts the moment the envelope leaves your hands, while hand delivery or fax counts only when it reaches the lender. Used well, it is one of the few places in consumer finance where you genuinely get to change your mind after signing, with your home and your money intact.
This guide explains a federal rule in general terms and is not legal advice. For a specific loan or deadline, confirm the details on your own closing documents and consider speaking with a qualified attorney or a HUD-approved housing counselor.
The fastest debt payoff plan is usually a bigger shovel.
Every payoff method works better with more income behind it. If your career has plateaued, finding work that matches your cognitive strengths can raise the number that matters most: what you can put toward the balance each month.
Find the career your brain was built forQuestions people ask
Does the right of rescission apply when I buy a house?
Usually not, but there is an important exception. A loan secured by the very home you are buying or building is a residential mortgage transaction, which Regulation Z exempts, so a standard purchase mortgage carries no right to cancel once you sign the closing documents. However, CFPB commentary preserves rescission when you borrow against a home you already live in to help acquire or build a different one. A bridge loan secured by your current principal dwelling is the classic example, and it can be rescindable even though the money is used to buy another home. So the key question is which home secures the loan, not just what the money is for.
How exactly do I count the three business days?
Start from the latest of three events: signing the note, receiving the Notice of Right to Cancel (two paper copies, or a single electronic copy if delivered under the E-Sign Act), and receiving all material disclosures. The day after that last event is day one. For rescission, Saturdays count but Sundays and legal public holidays do not, and your deadline is midnight of the third business day. The notice should show the exact date your window closes. Count the days yourself as well, and if your count does not match the printed date, do not simply assume one of them is right. A wrong expiration date can itself be a defective notice that affects your rights, so the safe move is to act by the earlier date and get advice about the discrepancy.
What if I just call my loan officer to cancel?
A phone call is not enough. The rule requires written notice. Use the cancellation form the lender provided, or any clear written statement that identifies the loan and says you are canceling. How you send it matters: a mailed notice counts the moment you mail it under section 1026.23(a)(2), while a fax or hand-delivered notice counts only when it reaches the lender. Send it in a way you can prove, such as certified mail with a return receipt, and keep a copy in case the timing is ever questioned.
Why do I sometimes hear about a three-year right to cancel?
If the lender never delivers the required Notice of Right to Cancel or all material disclosures, or delivers them with real errors, the normal three-day window can extend up to three years from closing, or until you sell or transfer the home, whichever comes first. The Supreme Court held in Jesinoski v. Countrywide (2015) that you preserve this extended right by mailing written notice within the three years, though lenders often dispute whether a violation actually occurred, which commonly puts the matter before a court.
What happens to my money and my home after I cancel?
Once you properly rescind, the lender's security interest becomes void and you are not liable for the finance charge on that loan. Within 20 calendar days of receiving your notice, the creditor must return any money or property given in connection with the transaction and take action to reflect that the security interest is terminated. Commentary explains the 20 days is when the creditor must begin that lien-termination process, not necessarily finish it, so clearing the lien from your title can take a bit longer. You then return any loan funds you received, putting both sides roughly back where they started, and a court can modify this order if the lender contests your right to rescind.
Does refinancing with my current lender limit the right to cancel?
It depends on who your lender actually is. The limited same-creditor exemption applies only when you refinance with the original creditor, the one your loan was first made payable to, or a company that took its place through a merger, consolidation, or acquisition. In that case only the new money beyond your existing balance, unpaid finance charges, and refinancing costs can be canceled. But mortgages are sold all the time. If your loan was assigned to a different holder and you refinance with that assignee, the assignee is usually not the original creditor, so the full right of rescission applies to the whole refinance. Ask directly whether your new lender is the original creditor or its corporate successor.
Keep reading
How to Win at Credit Card Rewards Without the Debt Trap
The 800 Credit Score Playbook: What Actually Moves the Needle
Debt Snowball vs Avalanche: The Interactive Showdown
The Flourish Letter
One smart money idea each week, charts included. Join free and get the printable 2026 Money Calendar in your welcome email.